A patient hears “your plan covers 80%” and assumes insurance will pay 80% of the dentist’s bill. That assumption can create an unexpected balance because the percentage may apply to the insurer’s allowed amount, which can be lower than the office’s fee.
To explain out-of-network dental benefits to patients, separate three questions: Can the patient receive care at your office? Does the plan provide benefits for that care? How much might the patient owe?
Answer those questions before treatment, using verified benefits and a written estimate. A useful explanation should cover both the expected cost and how reimbursement will reach the patient or practice.
What does out-of-network mean for dental insurance?
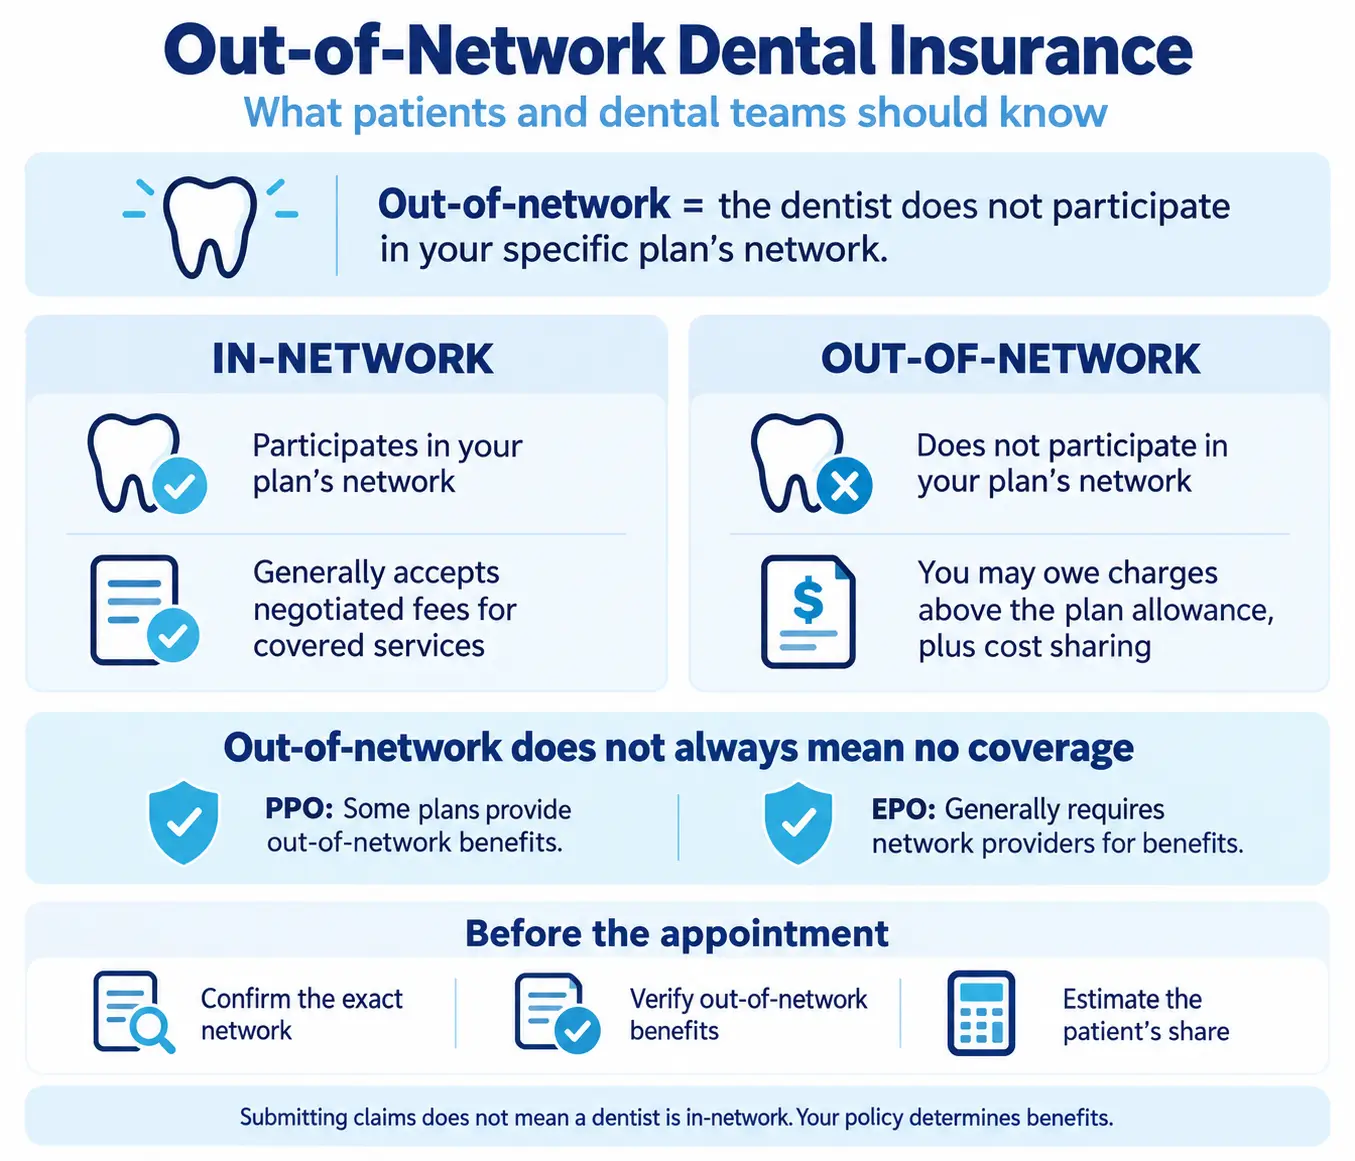
An out-of-network dentist does not participate in the patient’s specific dental network. Confirm the exact network before describing the office’s status; recognizing the insurance company’s name is insufficient.
Out-of-network does not automatically mean there is no coverage. Some PPO dental plans provide benefits for participating and nonparticipating dentists. Other arrangements, including dental EPO plans, generally require patients to use network providers to receive benefits.
Suggested wording for staff:
“Our dentist does not participate in your plan’s network. Your policy may still help pay for treatment here. We need to confirm your out-of-network benefits and estimate your share before your appointment.”
Avoid using the phrase “we accept your insurance” without clarifying what it actually means for the patient. A practice might submit dental claims for patients while remaining outside their network. Patients need to understand both facts.
In-network vs. out-of-network dental insurance
For covered services, an in-network dentist generally accepts a negotiated fee under the provider agreement. An out-of-network dentist may charge above the insurer’s allowance, leaving the patient responsible for the difference as well as applicable cost sharing.
Aetna’s 2026 FEDVIP dental brochure illustrates this distinction: network providers accept negotiated rates, while members using non-network providers may owe the difference between the plan allowance and the dentist’s fee. The patient’s own policy determines the applicable benefits.
How to explain out-of-network dental benefits to patients before treatment
Use a consistent conversation supported by a benefits verification record. Start with network status, explain the payment calculation, and finish with the office’s collection policy.
Verify benefits for the proposed services
Ask the payer about the actual treatment plan rather than requesting a general coverage percentage. A useful verification checklist includes:
- Eligibility and coverage dates.
- Out-of-network benefits for each proposed CDT code.
- The allowed dollar amount and plan payment percentage.
- Remaining deductible and annual maximum.
- Frequency limits, waiting periods, and replacement restrictions.
- Missing-tooth exclusions or alternative benefit provisions.
- Whether payment goes to the patient or dental provider.
For dentures, for example, ask about the proposed procedure, prior appliance history, replacement interval, and any applicable exclusion. Saying “dentures are covered” without further explanation can leave patients with important unanswered questions.
In the American Dental Association’s November 2025 ADA News article “Dear ADA: Out-of-network providers,” Shelley Olson, DDS, recommends asking for actual allowable amounts and relevant limitations. She also explains that reimbursement methods can differ between employer groups using the same carrier.
Record the verification date, representative or portal source, reference number, and unresolved questions. If the payer will not disclose an allowance, identify that uncertainty in the estimate rather than substituting an unsupported number.
Explain allowed amounts before discussing percentages
The insurance-allowed amount is the figure the plan uses to calculate benefits. It may differ from the dentist’s charge.
Some plans describe their reimbursement method using “usual, customary, and reasonable,” or UCR. Explain that this is an insurance calculation, not a promise to pay the office’s fee. The ADA’s undated resource “Dental Plan Benefits & Limitations” notes that a payer’s customary amount can fall below dentists’ usual fees for the same service.
Suggested wording:
“Your plan determines its payment based on its own allowed amount. We’ll display that amount separately from our fee so you can understand how we estimated your share of the cost.”
Show a dollar example
Consider this hypothetical calculation:
- Dentist’s fee: $200
- Plan’s allowed amount: $150
- Plan pays: 80% of the allowance
- Deductible: already satisfied
- Remaining annual benefit: sufficient
The estimated insurance payment is $150 × 80%, or $120.
The patient’s estimated responsibility is $200 − $120, or $80. That includes $30 in coinsurance and the $50 difference between the dentist’s fee and the allowance.
The patient therefore owes more than 20% of the office’s charge. This example follows the ADA’s explanation of out-of-network payment as the combined total of plan payment, deductible, coinsurance, and any remaining balance.
Label examples clearly. Actual calculations must follow the patient’s policy.
Explain the limitations that can change reimbursement
A coverage percentage provides only part of the estimate. Review the restrictions that apply to the proposed treatment.
Deductible and annual maximum
A deductible is the amount a patient must pay out of pocket before insurance benefits begin to apply to covered services subject to the deductible.
For plans with an annual benefit maximum, that maximum limits what insurance pays during the benefit year. It does not cap everything the patient might spend. The ADA’s undated patient resource “Choosing the Right Dental Plan for You” distinguishes these limits and explains other restrictions patients should review.
Use the remaining benefit amount, not just the original annual maximum, when preparing an estimate. Ask about pending claims that could change the available balance.
Frequency limits and alternative benefits
A procedure may belong to a covered category but be unpaid because the patient has already used the permitted benefit. An alternative benefit provision may calculate reimbursement using a less expensive treatment option.
Explain the specific restriction instead of simply saying “insurance denied it.” For example, tell the patient whether the issue concerns timing, replacement history, or the benefit allowed for another procedure. These are recognized dental plan limitations described in the ADA’s “Third Party Issue Tracker.
Tell patients who receives the insurance payment
Patients also need to understand the payment route.
Assignment of benefits authorizes payment to the dentist, but some carriers do not honor assignment for nonparticipating providers. Applicable requirements vary. Verify the arrangement before promising that insurance will pay the office directly.
If the practice requires payment at the appointment, explain that policy plainly:
“Payment is required at the time of your appointment, in accordance with our office policy. We’ll submit the claim to your insurer, who may reimburse you directly based on the benefits outlined in your plan.”
If the practice collects an estimated patient portion and waits for insurance, state how any remaining balance or credit will be handled.
Avoid promising a reimbursement date without a verified basis. Give patients a contact person and explain how the practice follows up on claims requiring additional information.
Use a written estimate without presenting it as a guarantee
Provide a treatment estimate showing the proposed procedures, office fees, expected insurance contribution, estimated patient responsibility, and amount due at the appointment.
Distinguish confirmed information from assumptions. An unknown allowed amount should remain visibly uncertain.
For treatment involving substantial expense, request a payer pretreatment estimate when available. Delta Dental of North Carolina’s undated guidance explains that this is an estimate of potential benefits, not a guarantee of future payment.
Ask the patient to explain the arrangement back:
“What amount do you expect to pay at your appointment, and who do you expect to receive the insurance payment?”
This question helps reveal misunderstandings before treatment. Document the discussion and provide a copy of the financial estimate.
How to explain dental insurance EOBs in plain language
Walk through the explanation of benefits alongside the office account:
- Identify the service and date.
- Compare the amount billed with the insurer’s allowed amount.
- Review the payment and any deductible.
- Explain the adjustment or denial reason.
- Reconcile the result with payments already received.
The ADA’s undated “Explanation of Benefits Statement” resource identifies remark codes as the place where payers explain processing decisions, including alternative benefits and documentation requests.
Investigate inconsistent figures before sending a revised bill. In its May 2026 ADA News article “Dear ADA: Out-of-network billing,” the ADA addresses EOBs that incorrectly suggest fee restrictions or no patient responsibility for nonparticipating dentists. An EOB discrepancy requires review, rather than an unexplained charge to the patient.
Does a frequency denial require a write-off?
A denial alone does not settle what the practice may collect. Review the network agreement, plan terms, denial explanation, and applicable law.
In the March 2026 ADA News article “Dear ADA: Noncovered services,” Liz Papineau, DDS, explains that a covered service can be unpaid because a frequency limit was exceeded. Contracted fee restrictions may still apply. Avoid treating every unpaid service as entirely excluded or automatically billable at the full fee.
What to include when notifying patients about a network change
A patient notification letter should state the affected network, effective date, and how patients can obtain an updated estimate. Explain whether the office will continue submitting claims and when payment will be due.
Review already scheduled treatment individually. Do not promise unchanged reimbursement or assume every patient has out-of-network coverage.
To explain out-of-network dental benefits to patients clearly, finish each discussion with four practical details: the office’s fee, the estimated insurance contribution, the expected patient payment, and who receives reimbursement. Put unresolved questions in writing and assign someone to follow up.